
What even is a sinking fund?
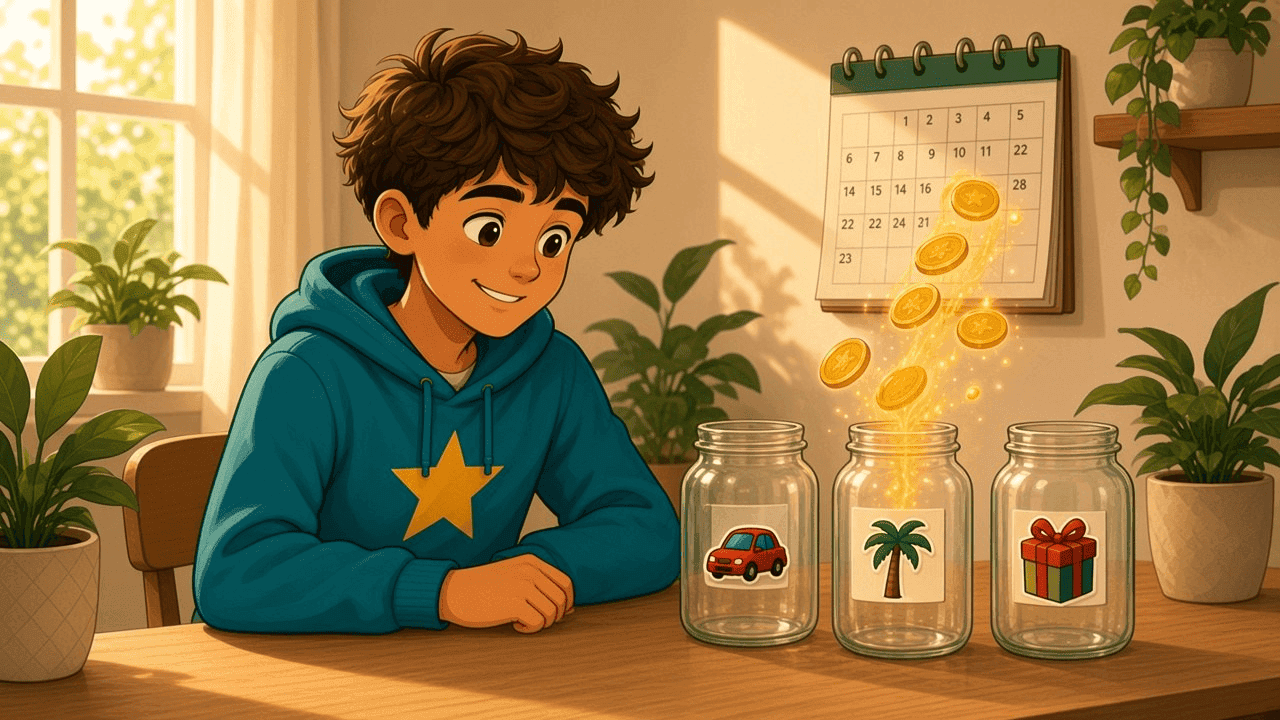
A named pot you drip into for known upcoming costs, not the same as emergency savings.
A sinking fund is a named pot of money you put aside, bit by bit, for something you already know is coming. You fill it a little from each pay so that bill doesn’t land as a shock when the due date arrives.
Why it’s not the same as emergency savings
Emergency money is for unknown surprises: your phone dies, you need an unexpected trip home, something breaks. A sinking fund is for known upcoming costs. You can see them on the calendar. You’re just choosing to drip cash toward them over time instead of scrambling when the due date hits. The buffer version: What even is an emergency fund?.
Picture a jar with a label: “car rego”, “holiday”, “Christmas gifts.” That’s the vibe. Mixing that jar with emergency cash gets messy. If you raid your emergency pot for Christmas, you’re less covered when a real surprise shows up. Keep the jobs separate.
What Aussies commonly sink for
Stuff that shows up every year or every few months works well:
- Car rego
- Holidays or a festival weekend with mates
- Christmas and birthdays
- New laptop or phone when yours is on its last legs
- Bond or moving costs if you’re planning a share house later
You name the pot, pick a rough target and a date, then divide by how many pays you have left. That drip becomes an intentional line in your budget, not “whatever’s left on Sunday.” The habit, for any goal: How do I even set money goals that stick?. A car or trip with maths: How do I even save for a car or holiday?.
How it fits a first-job budget
Say Christmas gifts will cost about $300 and you’ve got 10 pays until then. That’s $30 from each pay into a “Christmas” pot. Same idea for rego: if it’s $800 in six months and you get paid fortnightly, you’re looking at roughly $60–$70 a pay. Small, planned, boring in a good way. The gifts-and-birthdays version: How do I even save for Christmas?.
You still live. Friday with mates, coffee, the things that make the week feel like yours. Those stay in the plan. The sinking fund just means the big known costs don’t wipe you out when they arrive.
Keep it simple
You don’t need fancy apps on day one. A separate savings account (or even a note in your phone) with a clear name is enough. A high-interest savings account is a common parking spot. The magic is the drip: intentional slices from each pay, labeled for a real upcoming cost. The shorter, calmer map: Sinking funds without the spreadsheet stress.
If you use something like DoshHero Budget, you can give that drip its own line so it doesn’t get lost in the week’s spend. Named pots, clear jobs, still room to live. That’s the whole idea.
See also
What even is an emergency fund? · Sinking funds without the spreadsheet stress · What even is a high-interest savings account? · How do I even save for a car or holiday? · How do I even automate savings from each pay?
More in Budget
- What even is a budget?
- How do I even split my first pay?
- What even is net worth?
- What even is an emergency fund?
- Set up the DoshHero Budget
- Your first real budget (the three buckets)
- Sinking funds without the spreadsheet stress
- Living now while setting up later
- How do I even set up my first bank accounts?
- What even is car insurance?
- How do I even budget while living at home?
- How do I even budget when I rent with mates?
- What even is a high-interest savings account?
- How do I even automate savings from each pay?
- How do I even save for a car or holiday?
- How do I even set money goals that stick?
- What even is contents insurance?
- How do I even pick an everyday bank account?
- What even is inflation?
- How do I even build an emergency fund?
- How do I even save for Christmas (and birthdays) without the January hangover?
- How much of my pay should I actually save?
- How much board should I pay my parents?
- Am I behind? Savings and net worth at 20 and 25
- How do I even buy my first car without a loan wrecking me?
Dosh Drop