
How do I even pick a Super fund without spiralling?
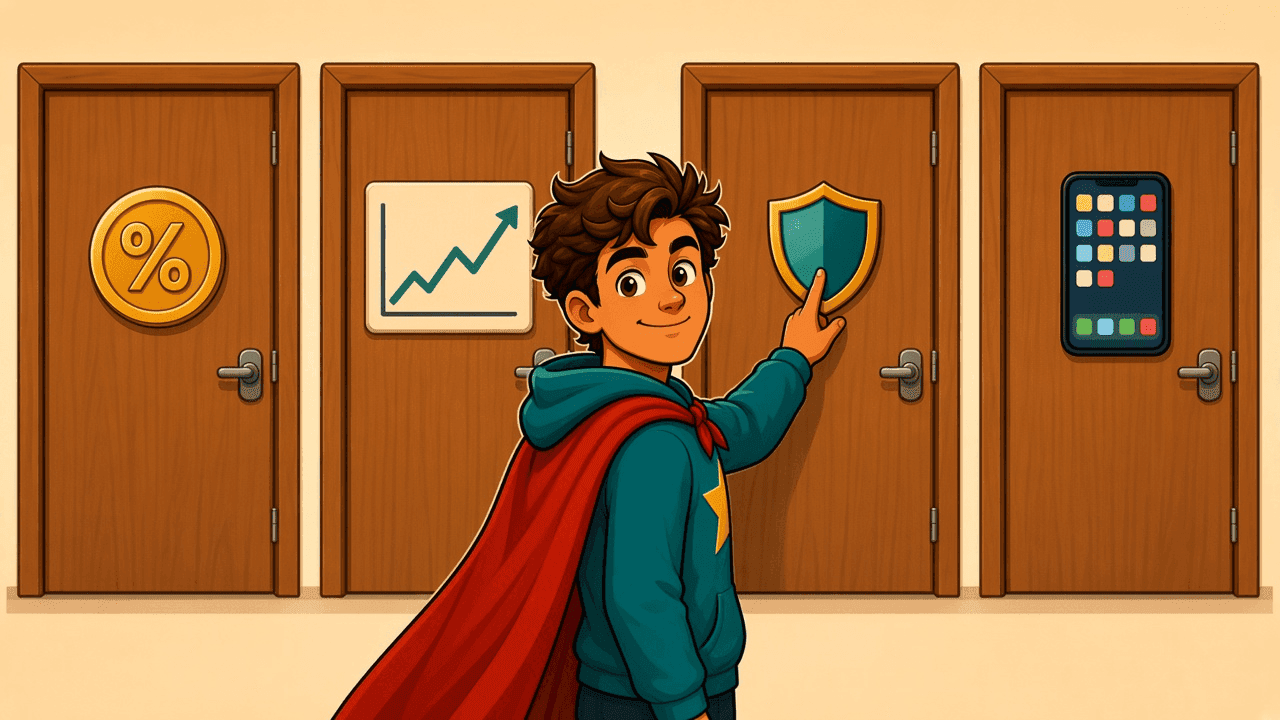
Fees, long-run performance, insurance, convenience. Pick one, skip the spiral.
Picking a Super fund means choosing where your Super balance lives and how it’s invested for the long run. If you never choose, you’re usually put in your employer’s default product: totally normal on day one, and not a fail.
You don’t need a finance degree or a weekend lost to comparison tabs. A simple frame is enough to stop the spiral.
Why this matters (without the lecture)
Super is a wealth engine: employer money goes in, it gets invested, and time does a lot of the heavy lifting. The fund is the vehicle. You’re allowed to start with “good enough for now” and refine later, while still living your life. First: How do I even check my Super is landing?.
A four-lens frame (use what fits you)
1. Fees on a small balance. Fixed dollar fees hit a tiny first-job balance harder than a bigger one. Glance at total fees on a low balance and a mid balance. Cheap isn’t the only lens. It’s one useful one.
2. Performance over time: look at long windows (think years, not last month). Past returns aren’t a promise of future ones. Compare similar options (don’t stack a cash-heavy mix against a high-growth mix and call one “better”).
3. Insurance: some cover can switch on automatically later (often around age 25 or a balance threshold), with premiums coming out of Super. Check whether you want that. Under 25 / small balances often start opt-in only. Rules have exceptions for some jobs. The plain tour: What even is insurance inside Super?.
4. Convenience. App that makes sense? Easy to see contributions landing? That counts. A fund you never open is harder to steer.
Default isn’t a tattoo
Workplace or award defaults exist because someone had to catch new starters. They’re a starting point, not a loyalty oath. You can usually switch later if you want, no panic energy required.
How to decide without drowning
- Write your four lenses in a note (fees, long-run performance, insurance, convenience).
- Pull two or three options max. Default plus anything you’re curious about.
- Score them roughly on those lenses.
- Pick one. Move on. Revisit in a year if your life changed.
Tools like the ATO’s YourSuper comparison can help you see fees and returns side by side. Use them as a map, not a homework assignment.
What this is *not*
- Not a ranking of funds.
- Not “you must switch tomorrow.”
- Not a reason to freeze your week.
It’s one calm wealth-building choice: put the engine somewhere sensible, then let time + contributions work while you keep living.
See also
How do I even check my Super is landing? · How do I even check my Super is actually being paid? · Super isn’t a grey-hair thing · How do I even salary sacrifice into Super? · What to actually check in your fund app
More in Super
- Super isn’t a grey-hair thing. It’s a pile with your name on it.
- How do I even check my Super is landing?
- How do I even check my Super is actually being paid?
- How do I even salary sacrifice into Super?
- Super 101 for your first job
- What to actually check in your fund app
- Consolidating later (when it might make sense)
- What even is insurance inside Super?
- What even is the Super guarantee?
- How do I even consolidate my Super?
- What even is the Super co-contribution?
Dosh Drop